Open Models and Frontier AI Valuations
Muse Spark Open and the outlook for the Anthropic IPO
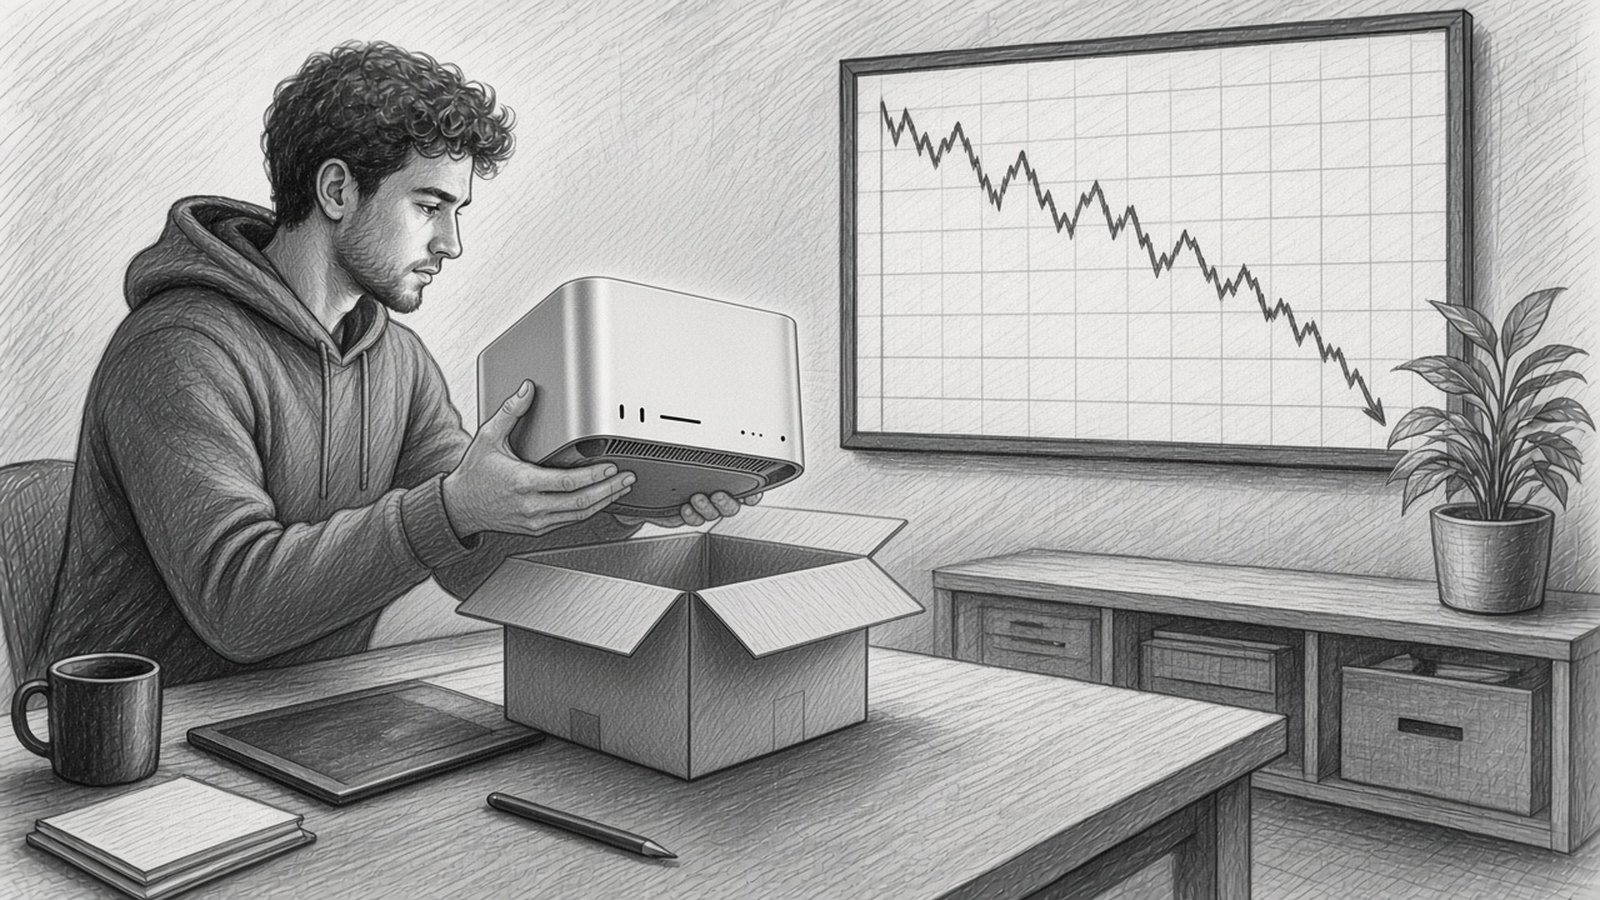
Meta’s new open model poses a question that reaches beyond benchmark scores: how much should investors pay for an AI company when increasingly capable alternatives are available to download? On October 15, Meta released Muse Spark Open, putting a powerful model in developers’ hands as Anthropic prepares for a reported November IPO. The timing makes the relationship between technological progress and financial value unusually tangible. 1 2
Open models could make AI more useful, more widely adopted and less profitable per unit of work at the same time. For frontier laboratories, whose business depends on developing and selling access to leading models, that combination matters. A company can keep adding customers while investors become less willing to pay a premium for its future earnings. Meta’s release strengthens the case for examining that possibility; it does not establish that Anthropic’s business is about to deteriorate.
The stakes are already substantial. Anthropic announced a $65 billion funding round in May at a $965 billion post-money valuation. On October 15, Reuters reported that some investors were discussing roughly $1.5 trillion for its IPO, below earlier expectations of about $2 trillion. Reuters connected the reassessment to slower sequential revenue growth and concerns about the cost of financing AI. These were investor discussions, not a final offering price. 2 3
The chronology matters. The investor meeting described by Reuters took place on October 14, before Meta’s release. Attributing the reported valuation shift to Muse Spark Open would therefore confuse an emerging competitive risk with an already documented financial debate. The question now is whether open models make investors more cautious about the profits they expect Anthropic to earn over the next decade.
Muse Spark Open is designed for coding and agents that perform multistep tasks. Meta describes a multimodal model with 816 billion total parameters, 42 billion active parameters and a context window of roughly one million tokens. Developers can download its weights, use hosting partners or run it on supported hardware. Meta also demonstrated a configuration using two M5 Ultra Mac Studios. 1
Those capabilities make the release relevant to commercial software, but the word ‘open’ needs care. This is an open-weight release under Meta’s own license. The license requires attribution and a separate agreement for model-as-a-service providers when the aggregate gross revenue of the licensee and its affiliates exceeds $20 million in a consecutive twelve-month period. The provision exempts internal use and ordinary products that incorporate the model without selling model access as a service. It is not a blanket revenue ceiling on every business using Muse. 4
Meta is also pursuing paid, hosted models. Three days before releasing Spark Open, it introduced Muse Wonder and Muse Wonder Full, describing them as its most capable models and distributing them through its API and Muse Code offerings. 5 The combination suggests a segmented market: broad access to strong capabilities, with a premium for the latest advances and the products built around them. Meta’s own strategy leaves room for paid intelligence.
Nor does the launch establish that Spark Open matches Claude on every important task. Meta’s model card compares it with other open models and shows mixed results across benchmarks. Its evaluation report explains that some coding comparisons use different agent software and self-reported results. 4 6 A buyer still needs to test the work it actually performs. A model that excels at one benchmark may need more retries, supervision or computing time in a particular deployment.
The economic challenge nevertheless begins well before perfect parity. Consider a software company that uses a premium model to classify support requests, summarize documents and resolve difficult coding problems. An open model that handles the first two jobs reliably could reduce its spending on the premium provider. The customer might continue buying the best model for complex engineering while moving routine work elsewhere. Revenue can migrate one task at a time, without a dramatic customer defection.
Even customers who never switch gain a stronger negotiating position when they can demonstrate a workable alternative. That changes the price a supplier can sustain. The most exposed revenue is likely to be spending on tasks that are easy to evaluate, easy to move and already performed well by several models. Revenue tied to difficult work with costly failures should be more resilient. This is a forecast about how buyers may behave, not a measured effect of a model released yesterday.
There is historical reason to take falling prices seriously. Stanford’s 2025 AI Index found that the inference cost of achieving GPT-3.5-level performance fell more than 280-fold between November 2022 and October 2024. 7 That finding concerns a fixed level of capability, not every frontier workload, and it does not isolate open models as the cause. It does show how quickly a once-premium capability can become inexpensive as hardware, algorithms and competing products improve.
For investors, the difficult question is how long each new advantage lasts. Training a leading model requires investment before the resulting service earns revenue. If comparable capabilities become widely available sooner, the laboratory has less time to recover that investment at premium prices. Sustaining leadership then depends on repeatedly discovering improvements that customers value enough to pay for. Faster research progress can expand the market while also accelerating the obsolescence of the models that generated yesterday’s revenue.
Meta has a different set of incentives from a company built primarily around commercializing AI. In his 2024 essay on open AI, Mark Zuckerberg argued that Meta benefited from stronger technology ecosystems and avoiding dependence on competitors’ platforms. He also emphasized that selling model access was not Meta’s business model at the time. 8 Its newer paid offerings complicate that distinction, but the strategic logic remains useful: a diversified company can benefit from making a technology cheaper if that technology improves its other businesses.
That is an uncomfortable competitive possibility for a frontier laboratory. A rival may be willing to give developers capabilities that the laboratory hopes to monetize. The resulting value can accrue to software companies, hardware suppliers and customers, even if the original model developer captures less of it. An expanding AI economy does not guarantee that every company at its center will earn exceptional returns.
The effect on valuation can be larger than the immediate effect on sales. Investors may lower revenue forecasts if customers move work to cheaper alternatives. They may also reduce the multiple they apply to the remaining revenue because margins look less durable. In a simple illustration, a 10 percent reduction in expected revenue combined with a 20 percent reduction in the valuation multiple lowers the implied value by 28 percent. Nothing in that arithmetic requires the business to stop growing.
Anthropic’s reported financials make the sensitivity concrete. According to Reuters, Anthropic told prospective IPO investors that it generated $16.8 billion in third-quarter revenue and was profitable on an adjusted basis. 2 Multiplying that quarter by four gives a $67.2 billion annualized revenue base. Against that denominator, equity values of $1.5 trillion and $2 trillion represent roughly 22.3 and 29.8 times revenue. Those are calculations for comparison, not established IPO multiples, forward revenue forecasts or enterprise-value multiples. Adjusted profitability also does not, by itself, establish GAAP profitability or free cash flow.
This comparison holds revenue constant to isolate the price investors place on it. In practice, investors would assess future growth, cash generation, dilution and financing needs together. Open competition could affect all of them. If price reductions outpace improvements in the cost of serving models, margins narrow. If lower prices unlock enough new demand, revenue can accelerate. If another costly training cycle is needed to preserve the premium, more sales may still leave less cash for shareholders.
There is, however, a substantial gap between downloading a model and replacing a commercial AI service. The software must run reliably under real workloads. Someone must operate the hardware, secure the deployment, monitor failures and maintain integrations. Meta’s desktop demonstration establishes another way to run advanced AI; it does not demonstrate that every business will find self-hosting cheaper than buying an API. Utilization and staffing can matter as much as the price of the weights.
Hosted open models also cost money. At publication, OpenRouter listed Muse Spark Open at $1.25 per million input tokens and $4.25 per million output tokens. 9 Those prices make a useful point about the distinction between access to weights and paid computation. They do not establish a like-for-like saving against Claude: models differ in reasoning effort, output length, latency and the number of attempts needed to complete a task. For a buyer, the meaningful unit is the total cost of a successful result.
That distinction is particularly important for agents. An inexpensive model that makes repeated mistakes can consume more computing resources and human attention than a more expensive one that finishes correctly. A meaningful advantage in reliability could preserve pricing power at the frontier. It could also allow a premium model to supervise cheaper models, with routine work delegated and the highest-value judgments retained. Open alternatives could then expand the system around the premium model instead of fully displacing it.
Anthropic’s product business offers another defense. Claude Enterprise includes Claude Code, Cowork, connectors and controls such as single sign-on, audit logs and data-retention settings. 10 These features create a service that organizations can put to work. Once a company has trained employees, connected internal systems and established operating procedures, switching carries a cost beyond the next API bill. The strength of that defense depends on whether customers value the complete product enough to keep paying for it.
The distinction also changes where competition occurs. Open models give other companies material for building competing coding assistants and workplace agents. They can challenge the application as well as the underlying model. Anthropic therefore needs evidence that its integrated products produce better outcomes, not merely evidence that enterprise customers need administration and security. Those needs create a market for services; they do not reserve that market for one supplier.
Cheaper AI could also enlarge that market. Businesses can automate tasks that were previously uneconomic, developers can experiment more freely, and new applications can bring additional customers to premium providers. Lower prices may be accompanied by falling inference costs, leaving margins intact. The bullish case depends on these gains being large enough, and on Anthropic retaining enough of the spending. Growth in total AI usage alone cannot settle either question.
For the IPO, the most informative evidence will concern customer economics. Are existing customers increasing spending after discounts? Are they adopting more Anthropic products or simply processing more tokens at lower prices? Does gross profit grow with usage? How much cash must be committed to maintain the next generation of models? Investors should also distinguish revenue that depends on a temporary performance lead from revenue supported by products customers would find difficult to replace.
Timing creates another complication. Software migrations, enterprise purchasing decisions and infrastructure deployments take time. A new release may have little effect on the next quarter’s revenue while changing investors’ expectations of earnings several years ahead. Conversely, an impressive announcement may produce limited commercial adoption once customers measure reliability and total cost. Download counts and launch benchmarks will be weaker evidence than sustained production use and contract renewals.
My assessment is that Muse Spark Open increases pressure on the valuation premium attached to frontier model scarcity. Its immediate effect on Anthropic’s IPO price cannot yet be measured, and the earlier investor reassessment had documented causes of its own. A more competitive market could coexist with a very large, successful Anthropic. The outcome depends on whether the company can convert its research lead into customer relationships and cash flows that survive the next capable release.
The most revealing question for prospective shareholders is what customers will continue paying Anthropic to do when good AI becomes widely available. If Claude remains the most effective way to complete valuable work, open models may expand the market it serves. If customers can obtain comparable results through interchangeable suppliers, the price of access should fall. Meta has made that choice more credible. Anthropic’s IPO will help reveal how much investors are prepared to pay for its answer.
Sources
Reporting and product details checked October 16, 2026. Model performance claims are attributed to their publishers. Economic implications and illustrative calculations are the author’s analysis.
- Meta AI Research. Introducing Muse Spark Open. October 15, 2026.
- Reuters. Investors temper Anthropic IPO valuation expectations over revenue growth slowdown. October 15, 2026; updated October 16; syndicated by Investing.com.
- Anthropic. Series H funding announcement. May 28, 2026.
- Meta. Muse Spark Open model card and Muse Model License. October 15, 2026.
- Meta AI Research. Muse Wonder. October 12, 2026.
- Meta. Muse Spark Open Evaluation Methodology. October 2026.
- Stanford HAI. The 2025 AI Index Report. 2025; highlights on inference costs.
- Mark Zuckerberg. Open Source AI Is the Path Forward. July 23, 2024.
- OpenRouter. Muse Spark Open pricing and providers. Accessed October 16, 2026; prices may change.
- Anthropic. Claude Enterprise. Accessed October 16, 2026.